A new era is underway. Geopolitical rupture and the need for sovereignty are redefining investment priorities, while investors are looking favorably at Europe as the continent rebuilds in energy, digital and transport. Ardian built early conviction around these themes and established positions across the full value chain, says Mathias Burghardt.
We are a year on from the rupture triggered by ‘Liberation Day’ in April 2025 and the subsequent shift in US policy. When I attended the Milken Institute Global Conference a month later, I could already sense that we were in a new era. Everything we have seen since confirms this shift has taken hold. The change is visible in the return of international investor appetite for Europe, as investors seek diversification and rebalance those portfolios that have been overexposed to the US. We experienced this directly in the fundraising for our latest infrastructure platform, where more than 60% of commitments came from outside Europe for the first time, especially from Asia-Pacific and the US. This sentiment is also reflected in the strongest year ever for private equity deal activity on the continent, with almost €650 billion in deal value. Europe is the best proxy to the US: the world’s second-largest economic bloc, with €27 trillion of GDP, a population of 500 million and a stable legal framework. While growth is still modest, inflation and interest rates returned to target levels last year. Investors also see valuation opportunities in Europe. If we take data centers as an example, price multiples are 22x in Europe versus 24x in the US. Combined with strong demand and growth opportunity, this clearly shows the attractiveness of European assets.
-
>60%
of commitments to our latest Infrastructure platform came from outside Europe
-
€33tn
European private wealth in cash and deposits – with potential to be deployed toward Europe’s strategic priorities
Sovereignty drives a new investment cycle
Sovereignty drives a new investment cycle
The shift toward regionalization and renewed emphasis on sovereignty did not begin last year, but it has acquired new urgency and is increasingly shaping investments. Energy independence and decarbonization, digitalization, AI supply chain including semiconductors, and connectivity are now treated as matters of sovereignty requiring sustained investment. The scale of the challenge was underlined in the landmark Draghi Report, which estimated annual investment needs of €750-800 billion for the region to bridge the productivity gap between Europe and the US. These themes are mutually reinforcing. As AI scales, demand for reliable power rises sharply, making energy a structural constraint. Meeting that demand requires significant investment in sustainable generation, grids and storage, while the AI hardware build-out drives parallel expansion in adjacent infrastructure and services. The result is a single, capital-intensive cycle binding AI, the energy transition and re-industrialization. We built early conviction around these shifts and established positions across the full value chain. In AI, this spans critical inputs through Ardian Semiconductor (targeting a €1 billion platform), digital infrastructure and data centers, and companies such as Artefact, a leader in data and AI consulting that our Expansion team exited for over €1 billion last year. In Buyout, we have around €1.8 billion invested in applied technologies. As a result, we have built one of the leading European platforms in these sectors and are well positioned to capitalize in a consolidating market that increasingly rewards scale and expertise.
“The shift toward regionalization and renewed emphasis on sovereignty did not begin last year, but it has acquired new urgency and is increasingly shaping investments.”
Need to mobilize European savings
Need to mobilize European savings
Europe will not meet its investment needs without private capital. Europeans are champion savers, yet only around 10% invest outside bank deposits, compared with 58% of US households participating in equity markets. As a result, some €33 trillion of European private wealth remains idle in cash and deposits. Redirecting even a portion of this capital toward productive investment is essential if Europe is to finance its strategic priorities. Recent regulatory progress, notably the ELTIF framework, is a step in the right direction.
Exits momentum accelerates
Exits momentum accelerates
With global M&A activity rebounding, 2025 became the second-strongest year on record for investment activity, surpassed only by 2021. Exit markets also reopened decisively, with exit values rising by more than 50% year on year. Against this backdrop, we deployed over $32 billion across 255 transactions, including the acquisitions of Diot-Siaci, Energia and Kering 5th Avenue. We also returned over $13 billion to our LPs through 33 exits. Recent examples such as Prosol and Hill Top Energy Center, each valued at over $1 billion, demonstrate our continued exit momentum.

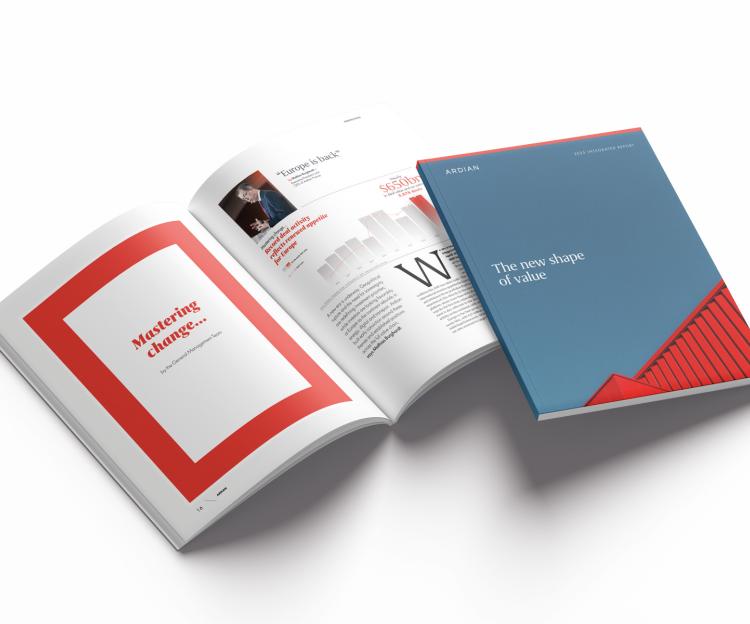
Ardian's 2025 Integrated Report
Ardian’s 2025 Integrated Report outlines how we create long term value for investors, portfolio companies and society. Discover insights from our General Management Team on the key trends shaping private markets and Ardian’s distinctive approach to value creation.